Should I Buy Now or Wait for Rates to Drop? An Honest Answer for Middle Tennessee Buyers
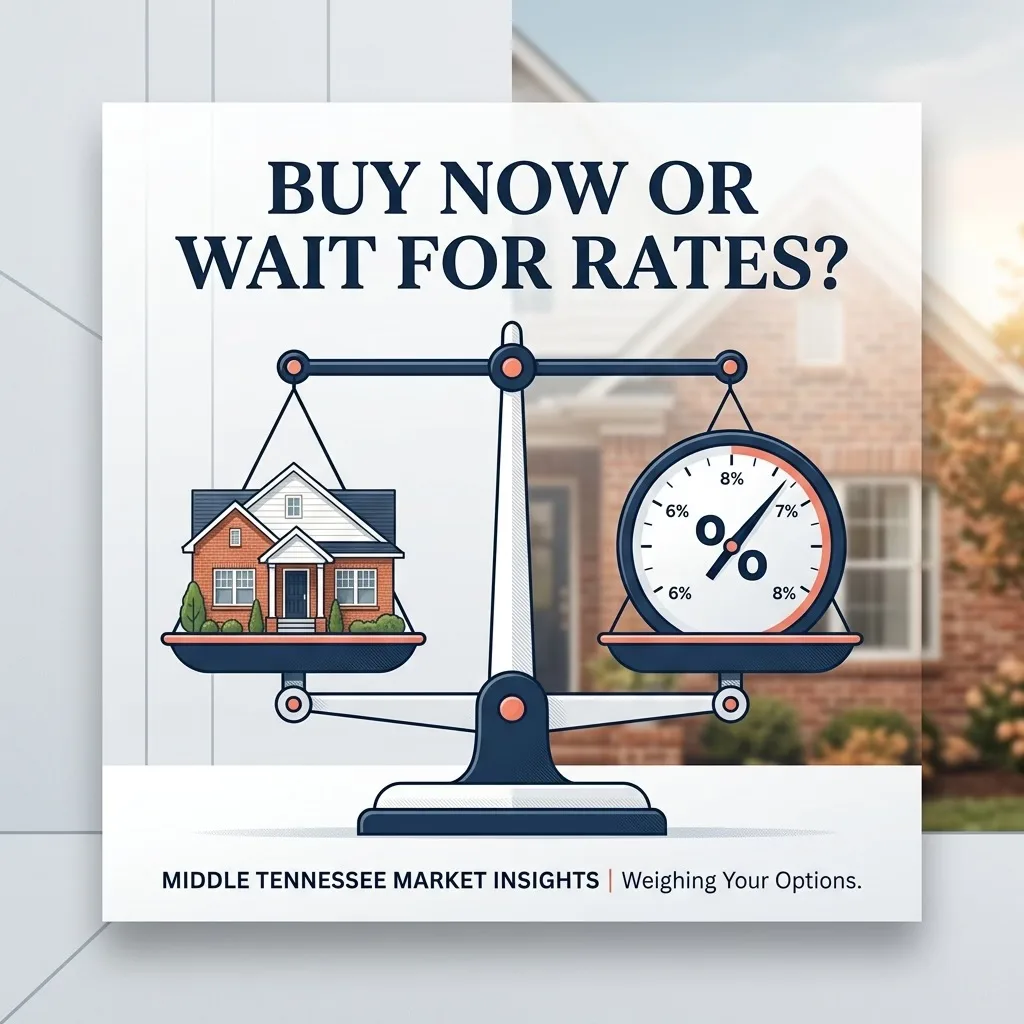
You are not imagining it: the first question buyers in Franklin, Brentwood, and across Middle Tennessee ask me this fall is whether they should buy now or wait for rates to drop. Here is the honest answer: no one can time interest rates, and this year waiting has already cost people real money. The average 30-year fixed mortgage climbed to 7.28 percent by October 1, 2026, up from 6.34 percent a year earlier, even as homes across Williamson County sat longer and sellers grew more willing to negotiate. If your finances can handle today's payment and your life is ready for a home, this is one of the better windows to buy that Nashville has seen in years, and here is why.
Why everyone is asking this right now
The rate-timing question is not new, but it has gotten louder. It topped the list of questions people asked the Greater Nashville Realtors Association last year, and it fills the comments on Middle Tennessee buyer groups, relocation forums, and neighborhood boards. The reason is easy to see: everyone hears about rates, and nobody sees the future.
What made 2026 different is direction. A year ago the average 30-year fixed rate was 6.34 percent, and plenty of buyers settled in to wait for the 5s. Instead, rates spent late summer climbing: 6.71 percent the first week of September, 6.76 the second, 6.95 the third, 7.03 the fourth, and 7.28 percent the first week of October, according to Freddie Mac's weekly survey. That is the highest reading since November 2023. Waiting for a drop, so far, produced the opposite.
Rates are high. That is not the whole story.
When rates move like this, prices usually have to do some of the adjusting, and in Middle Tennessee they are. Williamson County had about 1,756 active listings in early September, its highest count in roughly four years, up from about 1,599 a year earlier. Months of supply sat near 3.4, which is a balanced market: not flooded, but with real choices. Franklin's median sale price ran around $907,000 over the trailing 90 days, with roughly 587 homes for sale. Nashville's median was closer to $480,000.
Translate that into what it means at the kitchen table: homes are sitting longer, so sellers are more open to conversation. Price is negotiable. Closing costs are negotiable. Rate buydowns, where the seller contributes so you can lock a lower rate for the first years of the loan, are on the table more than I have seen since the market peaked in 2022. In 2022 a buyer often had to waive contingencies and hope. Today the same buyer can ask questions, run inspections, and negotiate.
What waiting actually costs
Here is the part nobody puts on the forum thread. Every month you wait, you are paying rent, and rents across Middle Tennessee keep climbing. Meanwhile price corrections in this market have been modest, inventory-driven pauses, not crashes, and the county is still growing. When rates do ease, the buyers who have been waiting will all hit the market at once, and competition returns. That is the pattern: when borrowing gets cheaper, buying gets busier, and prices firm back up.
The uncomfortable truth is that buyers who wait for both lower rates and lower prices usually end up with neither. I have watched this play out across market cycles. The people who did well locked in a home and a payment they could afford, and refinanced later when rates gave them the chance.
The decision that matters more than the rate
So how do you decide, practically? Stop trying to predict the Fed and start with three questions.
First, how long will you stay? Five years or more gives you room to ride out the ups and downs and to refinance when the opportunity comes. Second, can the payment fit today's budget without breaking it? If the number works at 7 percent with room to spare, you are in solid shape. If it only works with the rate at 5, that is a sign to wait and shore up your finances. Third, what is your life ready for? A child starting school, a growing family, a new job, a long-awaited move back home. A home bought for life reasons is almost never a mistake, at any rate.
And one principle worth repeating, because it is the whole game: you can refinance a house you bought. You cannot refinance the one you did not.
If you decide this is your window
If you are leaning toward yes, move like a buyer with leverage, because right now you have some. Get pre-approved so your offer means something. Ask for what you want: price, closing costs, a buydown, or a longer closing if you are selling one home to buy another. And work with someone who negotiates these neighborhoods daily, because the local details are where this market's deals are made. Our buying guide walks the full process step by step, and the market report has the numbers behind everything above.
The bottom line
Nobody can promise when rates will fall, and anyone who tells you they know is guessing. What I can tell you is what is true this week in Middle Tennessee: inventory is the highest it has been in years, sellers are negotiating, and a buyer who is ready can build real equity in a real home now instead of waiting on a number they cannot control. If you want to run the numbers on a specific home, or just talk through whether now is your moment, I would love to help. Reach out with any questions...we're here for you!
Sources
- Freddie Mac Primary Mortgage Market Survey – https://www.freddiemac.com/pmms
- FRED, St. Louis Fed – 30-Year Fixed Rate Mortgage Average in the United States
- Freddie Mac press release, September 24, 2026 – Mortgage rates average 7.03%
- Trading Economics – US mortgage rates climb further in October
- Bankrate – Compare today's 30-year mortgage rates
- Where to Live in Nashville – Williamson County market data and months of supply
- Dyad Real Estate – Franklin TN median home price 2026
- NewsChannel5 Nashville – Top questions about the housing market, asked of the Greater Nashville Realtors Association
- r/RealEstate – Is it dumb or smart to buy a house right now in Nashville with these interest rates?
REAL Broker
TN Lic: 372786